


Usually 12 months or less, repaid when your existing home sells.

Secure the next place without waiting for your current one to settle.
How a Bridging Loan Works
A bridging loan lets you buy your next home before your current one has sold. The lender uses the equity in your existing property as security and covers the gap between the two settlements, so you are not forced to sell first and rent in between, or miss the place you want while you wait.
-
Peak debt: the lender works out your existing loan plus the new purchase, and that combined figure is your peak debt
-
End debt: once your current home sells, the proceeds pay down the peak debt, and what remains becomes your ongoing home loan
-
The bridging period: usually 12 months or less, although some lenders offer longer terms
-
What lenders look at: this varies by lender, but generally the equity in your current home, the savings you hold, and your ability to service the ongoing loan once your existing home has sold
What a Bridging Loan Costs
Bridging finance costs more than a standard home loan, and it is worth understanding why before you commit. You are carrying two debts at once for a period, and lenders price that risk accordingly. The total cost depends on how long the bridging period runs and how your lender structures the interest.
-
Interest rate: usually higher than a standard home loan, and charged on the peak debt
-
How interest is handled: some lenders capitalise it onto the loan so you make no repayments during the bridging period, others require you to service it
-
Standard loan costs still apply: application fees, valuations on both properties, and legal costs
-
The real variable: how long your existing home takes to sell, since a longer bridging period means more interest
Which Lenders Offer Bridging Loans?
Most of the major banks offer bridging finance, but they structure it very differently. Some capitalise the interest so you make no repayments while bridging, others expect you to service both debts. Bridging periods, maximum peak debt and how they assess your expected sale price all vary. That is why the same situation can get very different answers depending on who you ask.
-
The major banks all offer some form of bridging finance, with different terms and conditions
-
Smaller lenders and non-banks can be more flexible on timeframes and serviceability
-
What matters is matching the structure to your situation, not just the rate
-
We compare across our lender panel rather than working from one bank's policy
Bridging Finance for Moreton Bay Homeowners
Most bridging loan specialists operate nationally, so the person assessing your situation has never seen your suburb. Kyle is based in Caboolture and works across the Moreton Bay region, which matters when a lender is weighing up how realistic your expected sale price is and how long your home is likely to sit on the market.
-
A local read on what your current home is realistically worth and how quickly it is likely to sell
-
Straight answers on whether bridging is the right move or whether another option suits you better
-
You deal directly with Kyle from the first conversation through to settlement, not a call centre
Ask Kyle
Common Bridging Loan Questions
What happens if my current home does not sell in time?
Talk to your lender early rather than waiting. Most will consider an extension, though it will cost more in interest. Some people also reduce their asking price to move the sale along. It is the main risk with bridging, which is why the expected sale price needs to be realistic from the start.
Do I make repayments during the bridging period?
It depends on the lender. Some capitalise the interest onto the loan so you pay nothing until your current home sells. Others expect you to service the debt throughout. This is one of the bigger differences between lenders and worth getting right.
How much can I borrow with a bridging loan?
It comes down to the equity in your current home, the price of the property you are buying, and what the lender will accept as peak debt. Most want to see a reasonable buffer between your combined debt and the value of both properties.
Is a bridging loan better than selling first and renting?
Neither is automatically better. Bridging costs more in interest but means you do not move twice or risk missing the property you want. Selling first is cheaper and lower risk but you may be renting for months. It comes down to your situation and how the numbers stack up.
Meet our Team
Kyle Downey
Principal Broker
Phone: 0493 010 111
Email: kyle@highpointfinance.com.au
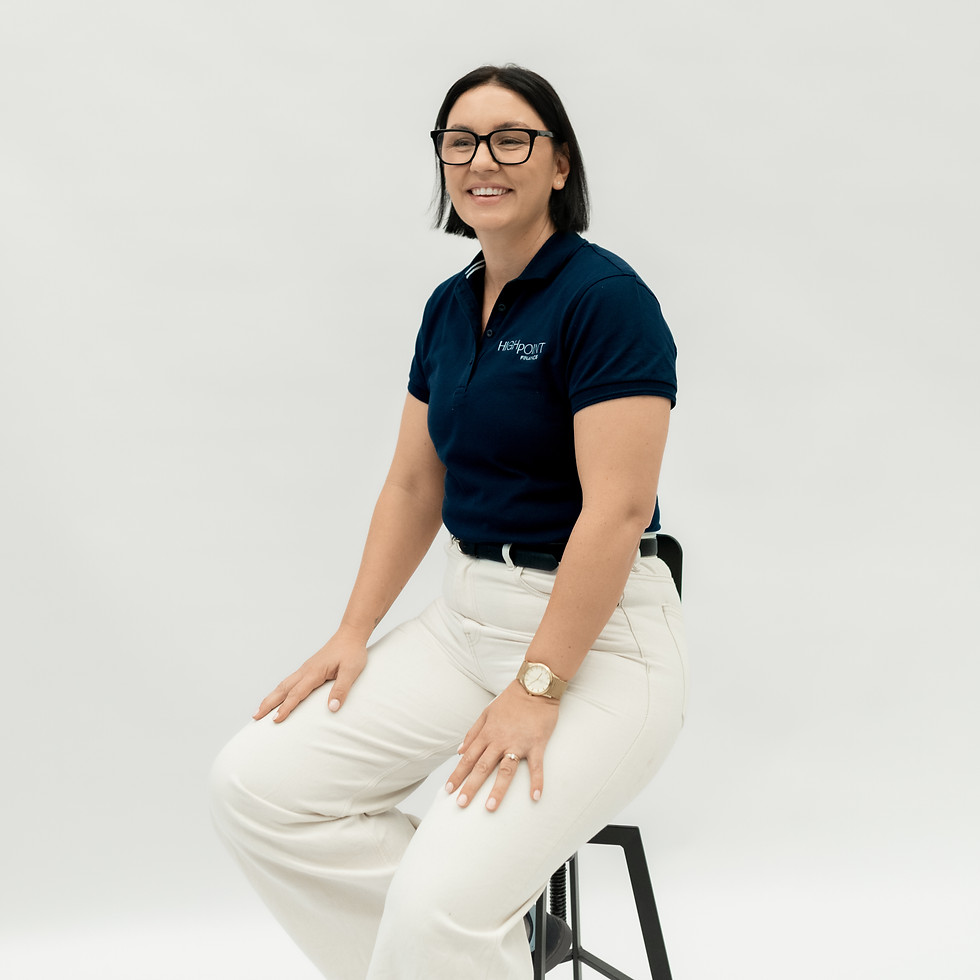
With 12 years of lending experience at one of the big four banks, Kyle has helped hundreds of first home buyers understand their options and get into their first place with confidence. He knows exactly what lenders look for, and takes the time to explain every step in plain English, so you always know where you stand.
Megan Downey
Broker Support
With a keen eye for detail, Megan assists with paperwork, applications and regular client updates, helping make the process feel simpler and less stressful. Megan is also dedicated to providing clients with an annual home loan review, helping them stay informed about their current loan, interest rate and available options as their needs or the market change.
Our Partners
CONTACT US
Get in touch today
When we help you with your borrowing needs, we consider you to be a client for life. We want you to be confident that you are working with professionals who have your best interests in mind now and in the long term.
We have many years of experience in finance and professional mortgage broking. Our aim is to find you the best loan for your needs, and to make the process as simple and transparent as possible.
Please get in touch with us today.
The privacy of your personal information is important to us. By providing your personal information to High Point Finance, you consent to be contacted by a representative of High Point Finance from time to time for marketing purposes. We will use your contact details to send you direct marketing communications including offers, updates and newsletters that are relevant to the services we provide. We may do so by mail or electronically. You can unsubscribe by notifying us and we will no longer send this information to you. Click <here> to view our full Privacy Policy.
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Consider whether it's right for you, and seek independent financial and legal advice before making a decision.