

Meet Kyle Downey, 12 years' bank lending experience, now on your side.

What lenders check, what you need to provide, how long it takes.

Understand your borrowing position before you start looking.
CALCULATOR
Use our mortgage calculators to estimate how much you can borrow.
We’ve designed these calculators to give you a better insight into how the lenders will view your loan application.
The information provided by the calculator is intended to provide illustrative examples based on the stated assumptions of your input.
Results are a guide only and do not constitute financial advice or any guarantee that you will be approved for a loan by a lender.
You should always discuss your individual circumstances with a representative of High Point Finance before placing your deposit or purchasing any property.
What Affects How Much You Can Borrow?
Lenders do not all arrive at the same number. They assess your income, your existing commitments and your living expenses against their own policy, and that policy varies more than most people expect. The same application can come back tens of thousands apart depending on who you take it to.
-
Income and commitments: your income, how stable it is, and existing debts including credit card limits even when you never use them
-
Living expenses and dependants: lenders apply a benchmark, and children shift the number significantly
-
Lender policy: overtime, bonuses, casual income and self-employment are all treated differently from lender to lender
What Is Lenders Mortgage Insurance (LMI)?
Lenders mortgage insurance, or LMI, is a one-off premium that protects the lender, not you, if a loan can't be repaid and the property sells for less than what's owed. For most standard residential properties, lenders charge it when you borrow more than 80 percent of the property's value, which usually means a deposit of less than 20 percent.
For some property types that lenders see as non-standard, such as student accommodation or rural properties, LMI can apply from 60 or 70 percent of the property's value. There is a smaller market for these properties, so lenders treat them as higher-risk security.
LMI isn't necessarily a reason to put your plans on hold. For many buyers it's the trade-off that gets them into the market sooner rather than spending more years saving while prices move. What matters is knowing what it will cost you and whether there's a way to reduce it or avoid it altogether.
What affects the cost of LMI?
-
Your deposit size. The smaller your deposit compared with the property value (your loan-to-value ratio, or LVR), the higher the premium.
-
How much you borrow. Larger loans attract a larger premium.
-
The lender. Each lender works with its own insurer and pricing, so the same loan can cost noticeably different amounts in LMI.
-
Your circumstances. Things like self-employment or buying an investment property can change the premium with some lenders.
Ways to avoid or reduce LMI
-
Save a 20 percent deposit. For most standard residential properties, borrowing 80 percent or less of the property value means LMI generally won't apply. Some property types need a larger deposit, so it's worth checking before you commit.
-
Use a government scheme or grant. Under the Australian Government's First Home Guarantee, eligible first home buyers can buy with as little as a 5 percent deposit and pay no LMI. The Family Home Guarantee helps eligible single parents and legal guardians buy with a 2 percent deposit. If you're buying or building a new home in Queensland, the Queensland First Home Owner Grant can add to your deposit. Property price caps and eligibility rules apply, and Kyle can access lenders for these programs.
-
Check for a professional waiver. Some lenders waive or discount LMI for eligible professionals, such as medical, legal and accounting professionals.
-
Use a family guarantee. A family member may be able to use equity in their own property as extra security, which can remove the need for LMI. Kyle has extensive experience arranging family guarantee loans.
-
Add it to your loan. If LMI does apply, many lenders let you add the premium to the loan rather than pay it upfront. Keep in mind you'll then pay interest on it over the life of the loan.
The right option depends on your income, your deposit and the property you're buying. Kyle can show you what LMI would cost across different lenders and whether you qualify for a way to avoid it, before you commit to anything.
What Happens When You Get Pre-Approved?
Pre-approval is the step between working out what you could borrow and actually making an offer. A lender reviews your position properly and indicates in principle what they would lend, which tells you what price range is realistic and shows agents and sellers you are serious.
-
What you provide: payslips, bank statements, ID and details of any existing debts
-
How long it takes: usually a few business days once we have your documents, though it varies by lender
-
How long it lasts: most lenders hold it for around three months, and it can usually be renewed
-
What it is not: pre-approval is not a guarantee, and it is subject to the property and final checks
Ask Kyle
Common Home Loan Borrowing Questions
How much can I borrow?
It depends on your income, your existing debts and living expenses, and the lender's own policy, which varies more than people expect. The calculator above gives you a guide. For a real figure, Kyle can run your numbers against actual lender criteria.
What would my repayments look like?
That comes down to the loan amount, the interest rate and the term. The calculator above will give you an estimate. Worth also checking what the repayments look like if rates move, rather than just at today's rate.
How much deposit do I need?
For most standard residential properties, lenders look for 20 percent to avoid lenders mortgage insurance, though some property types need more. There are loans available with less, and government schemes and grants can reduce it further for eligible first home buyers. What you need depends on the lender, the property and your situation.
Can I find out what I could borrow without affecting my credit score?
Yes. Working out your borrowing capacity is just a conversation and some numbers, with no credit check involved. A credit enquiry only happens later, when you apply for pre-approval.
Meet our Team
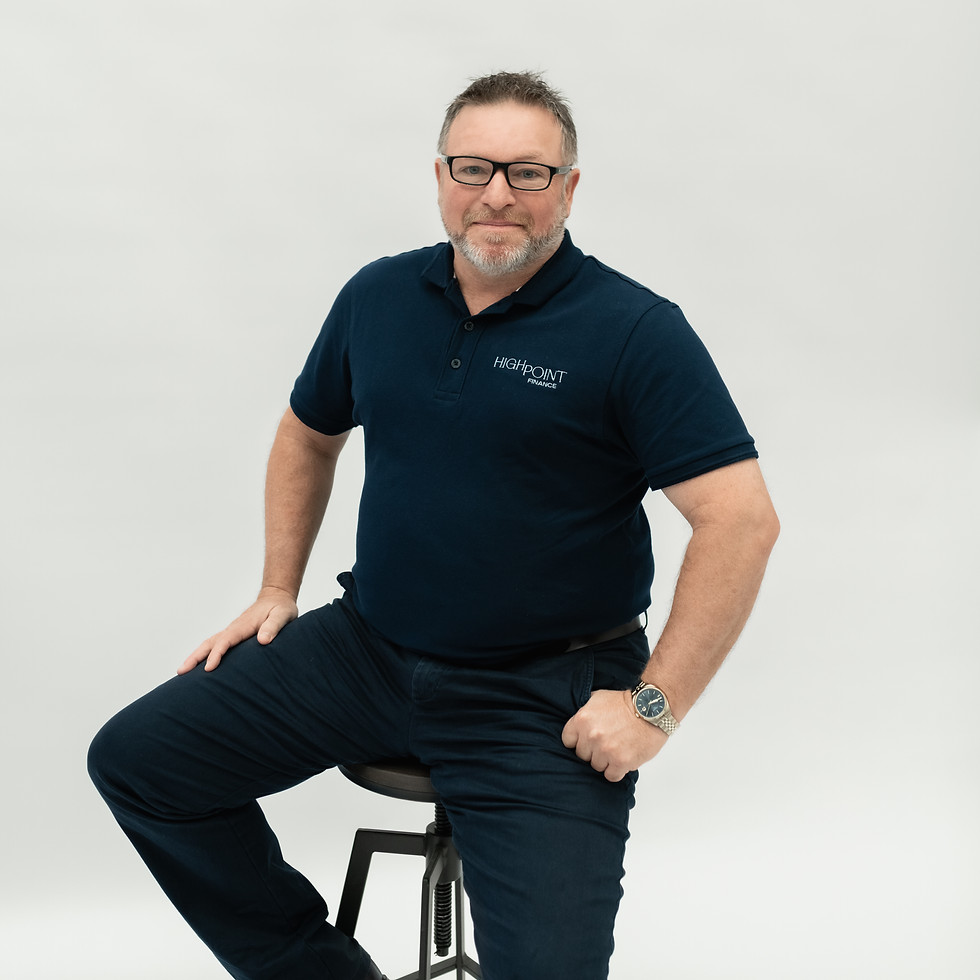
Kyle Downey
Principal Broker
Phone: 0493 010 111
Email: kyle@highpointfinance.com.au
With 12 years of lending experience at one of the big four banks, Kyle has helped hundreds of first home buyers understand their options and get into their first place with confidence. He knows exactly what lenders look for, and takes the time to explain every step in plain English, so you always know where you stand.
Megan Downey
Broker Support
With a keen eye for detail, Megan assists with paperwork, applications and regular client updates, helping make the process feel simpler and less stressful. Megan is also dedicated to providing clients with an annual home loan review, helping them stay informed about their current loan, interest rate and available options as their needs or the market change.
CONTACT US
Get in touch today
When we help you with your borrowing needs, we consider you to be a client for life. We want you to be confident that you are working with professionals who have your best interests in mind now and in the long term.
We have many years of experience in finance and professional mortgage broking. Our aim is to find you the best loan for your needs, and to make the process as simple and transparent as possible.
Please get in touch with us today.
The privacy of your personal information is important to us. By providing your personal information to High Point Finance, you consent to be contacted by a representative of High Point Finance from time to time for marketing purposes. We will use your contact details to send you direct marketing communications including offers, updates and newsletters that are relevant to the services we provide. We may do so by mail or electronically. You can unsubscribe by notifying us and we will no longer send this information to you. Click <here> to view our full Privacy Policy.